
KPR — Kredit Pemilikan Rumah — is an Indonesian bank mortgage available to KTP holders, including WNI living and earning overseas. A salary in USD, SGD or AUD doesn't change that.
KPR approval is subject to bank assessment and applicable requirements.
Can I really get an Indonesian mortgage for a villa in Bali? Does my overseas salary count? Is the title real? Fair questions — they're the reason this page exists. Below is the whole picture, including the parts a brochure won't lead with.
Jimbaran Hill is a villa development by Avilla Development, a Bali developer building since 2005. Three-bedroom villas on a quiet hillside in Jimbaran — minutes from Universitas Udayana, Udayana Hospital, and the beach. Every villa is sold on SHM — Sertifikat Hak Milik, freehold title, the strongest form of property ownership in Indonesia, and one only Indonesian citizens can hold. That is exactly why this project works with KPR.
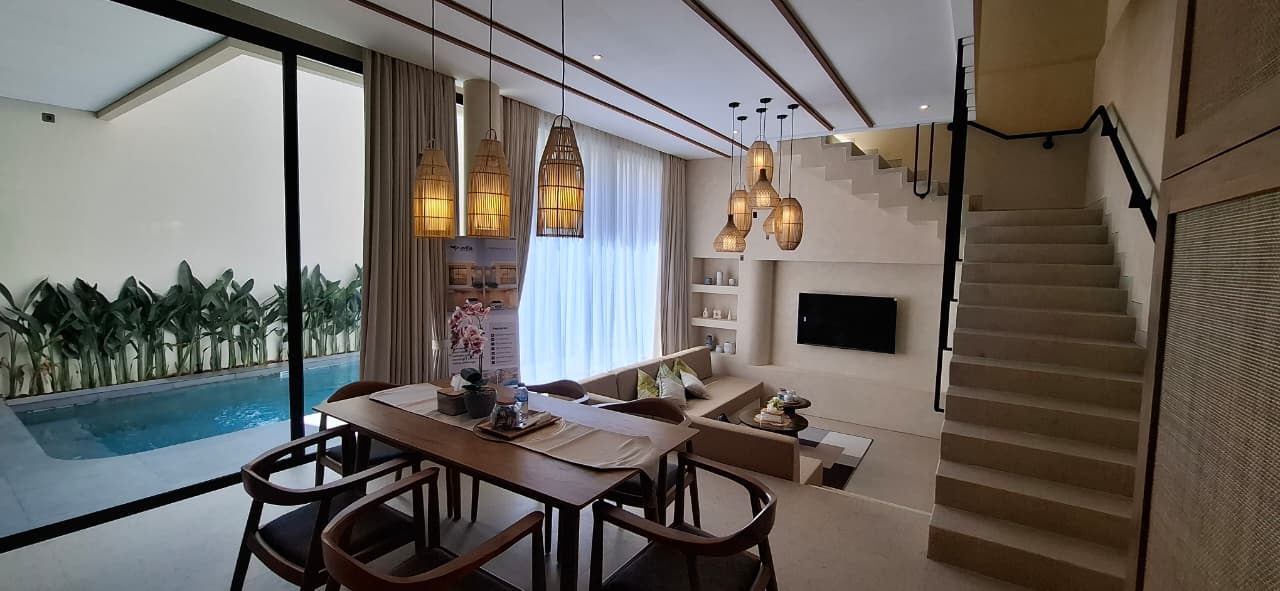
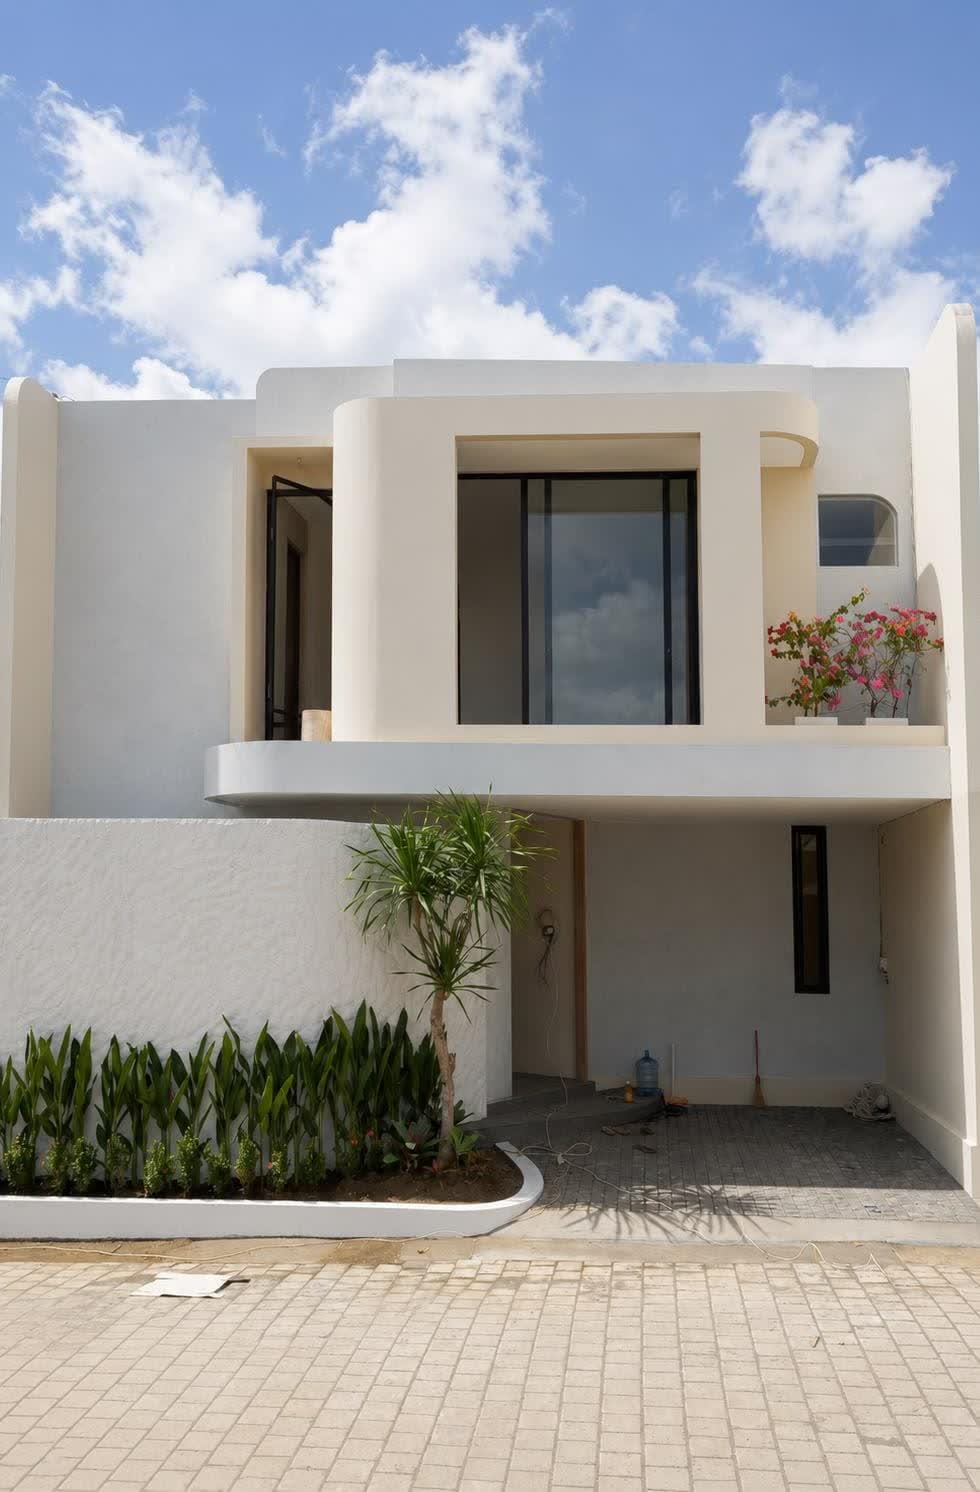
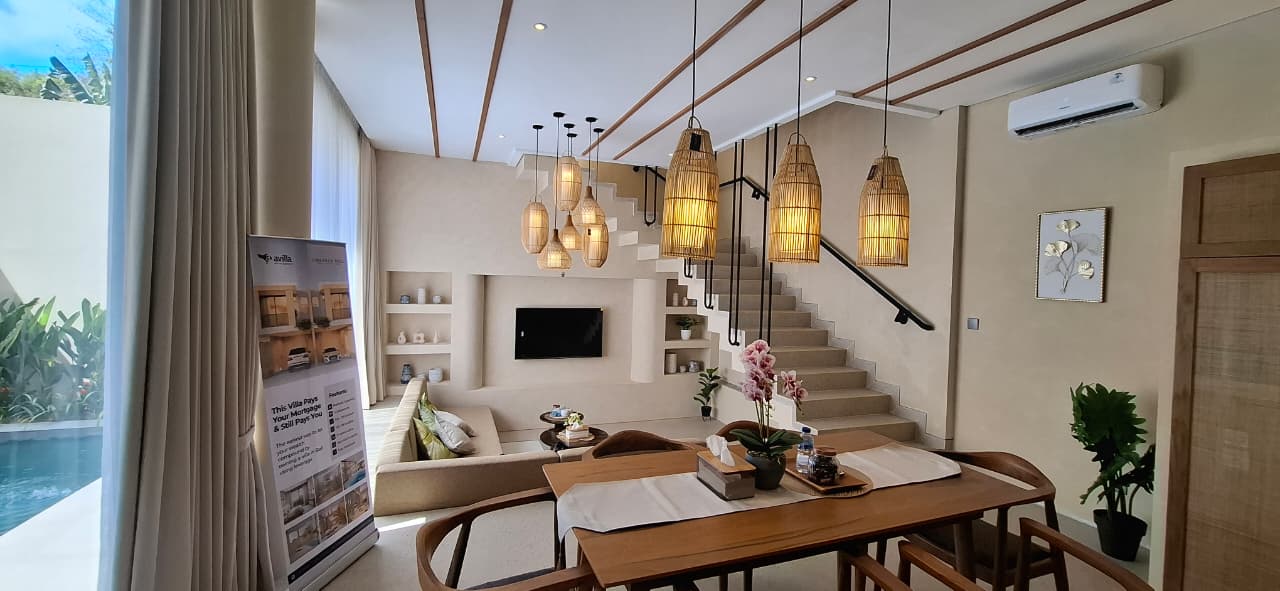
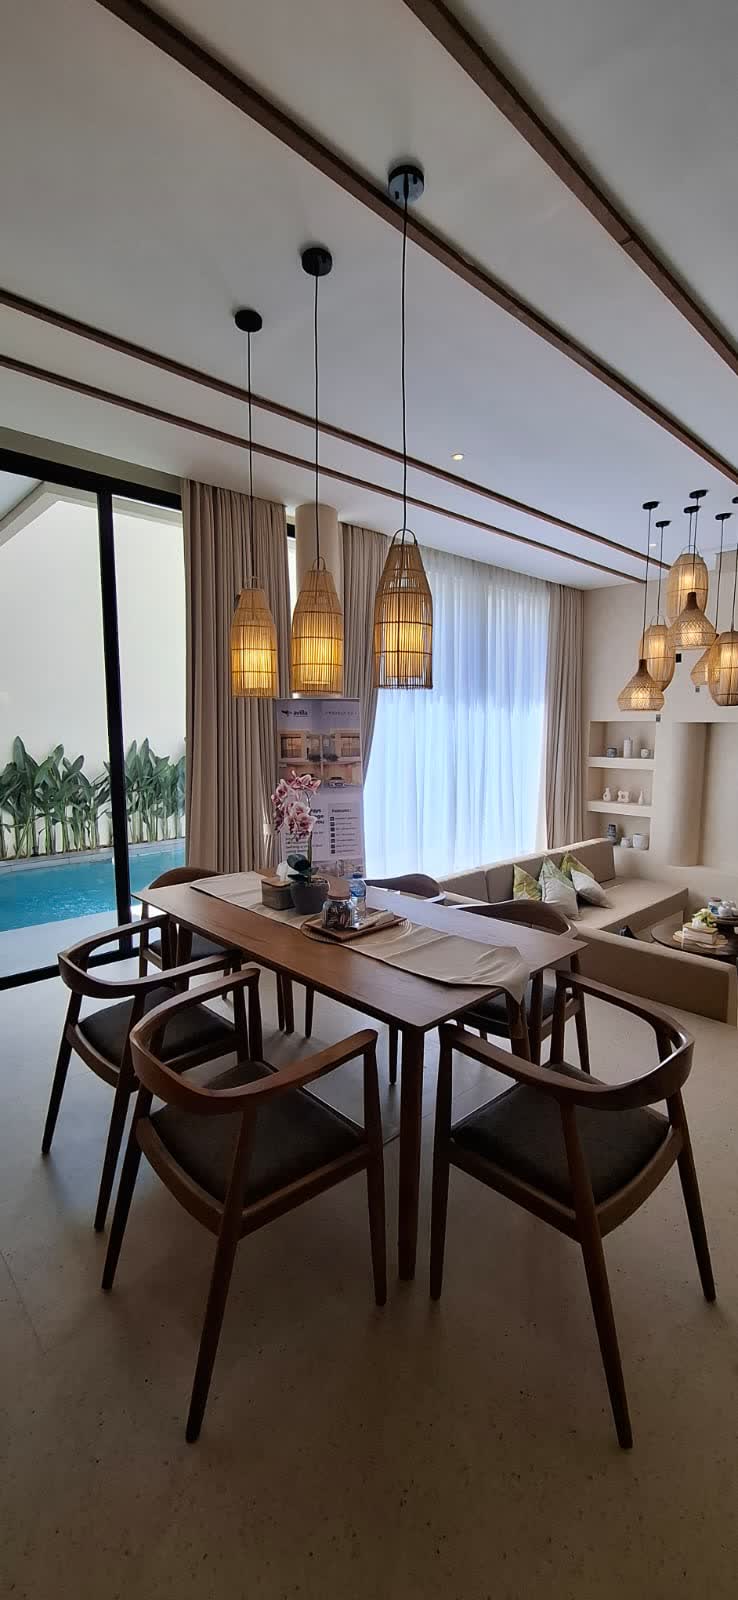
Cyra — show unit, photographed. Not renders.
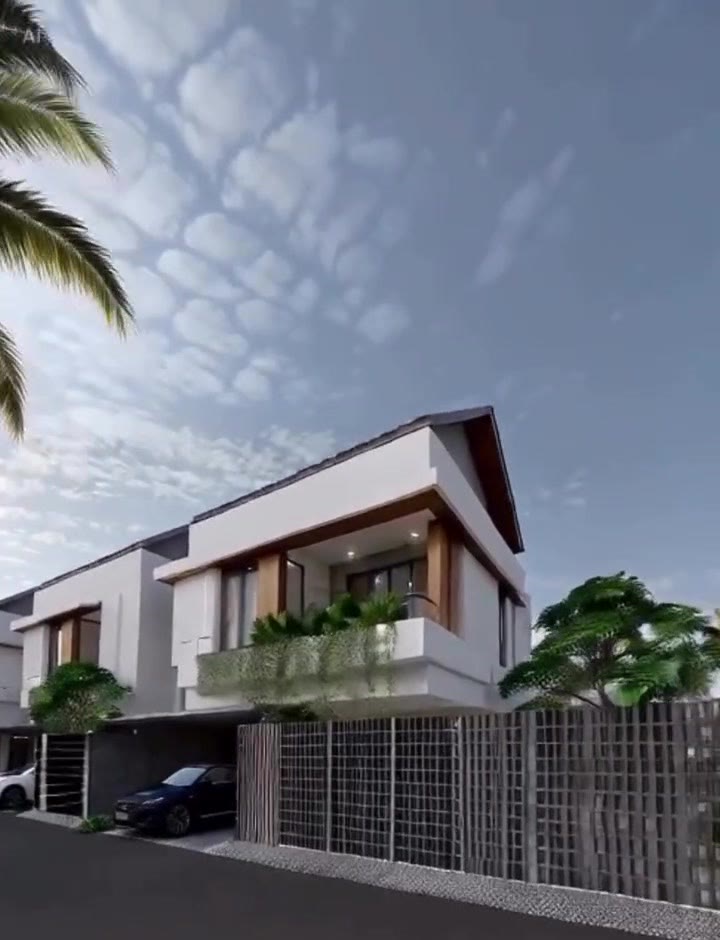
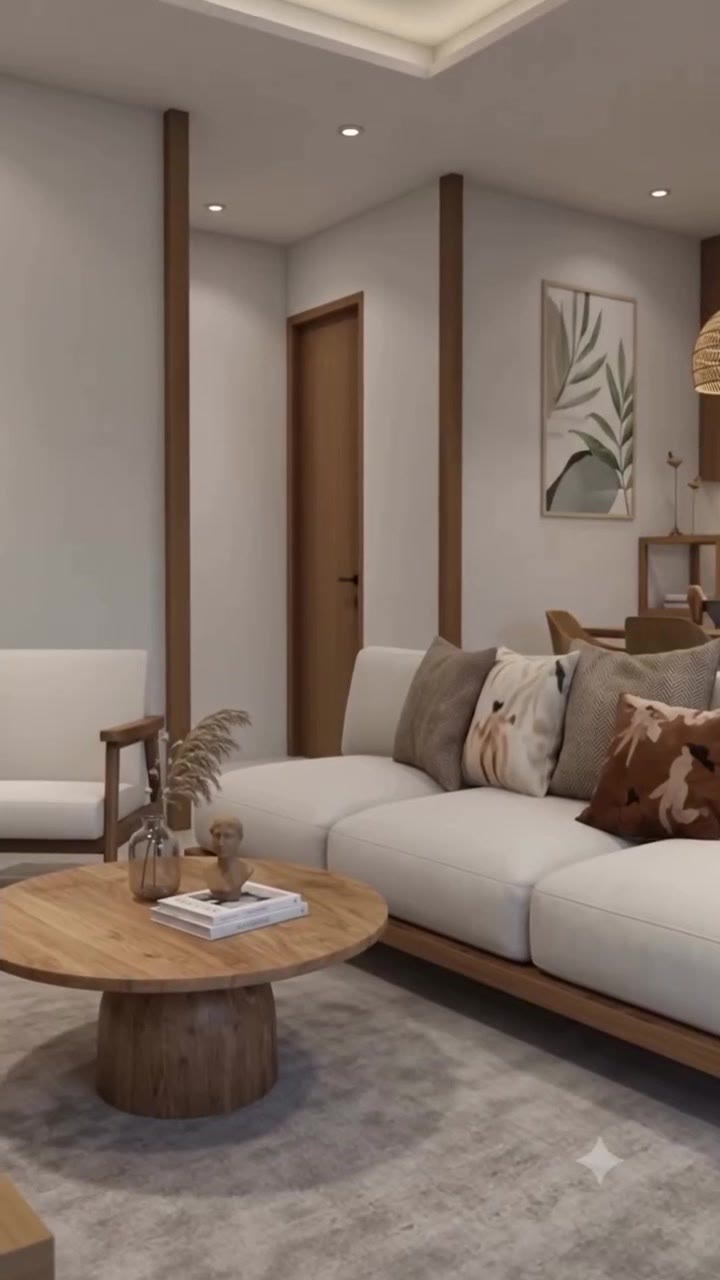
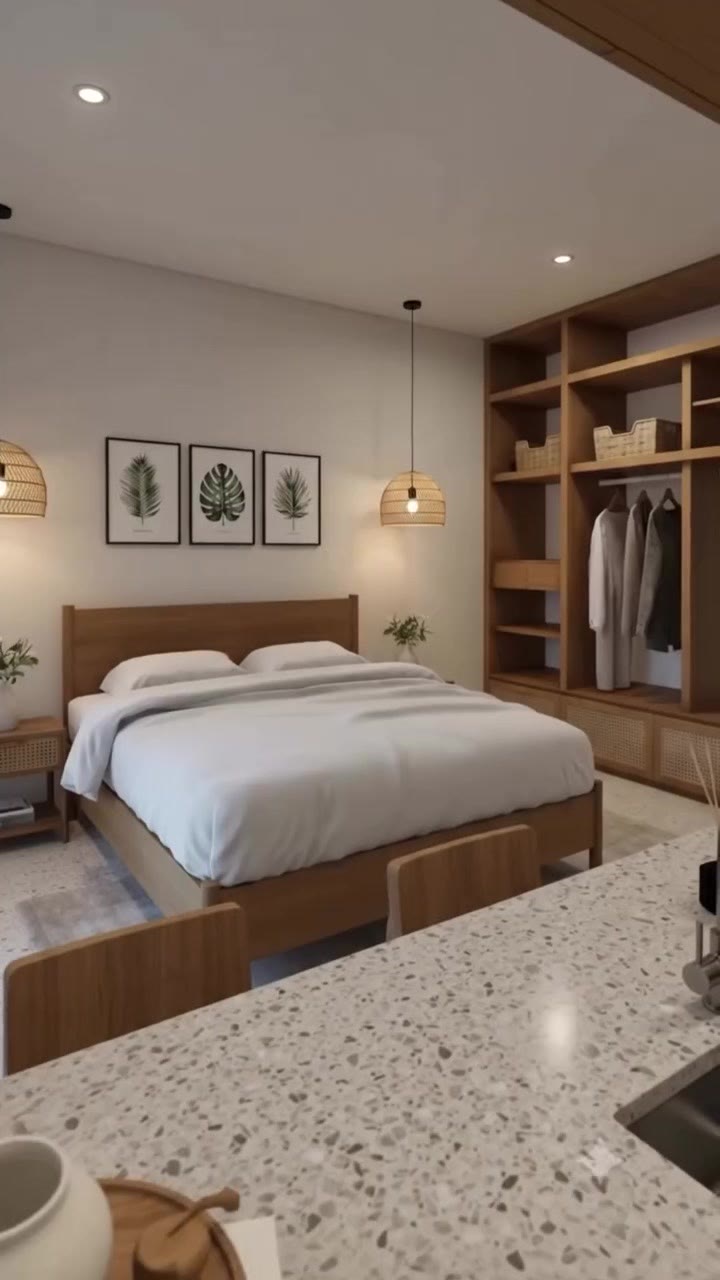
Aira — renders, labeled as such. A different, more minimalist design than Cyra. There is no Aira show unit yet.
From IDR 2.82B — ask us for the live unit list
From IDR 3.34B — C9, C15 & C17 available
This is not a promise on a masterplan. The estate — the kawasan — is finished: roads, walls, landscaping, and gated security are in, and you can walk it today. It sits minutes from Sidewalk Mall and GWK, about 20 minutes from the airport. See the exact location on Google Maps — or ask us for a live virtual tour on a video call.
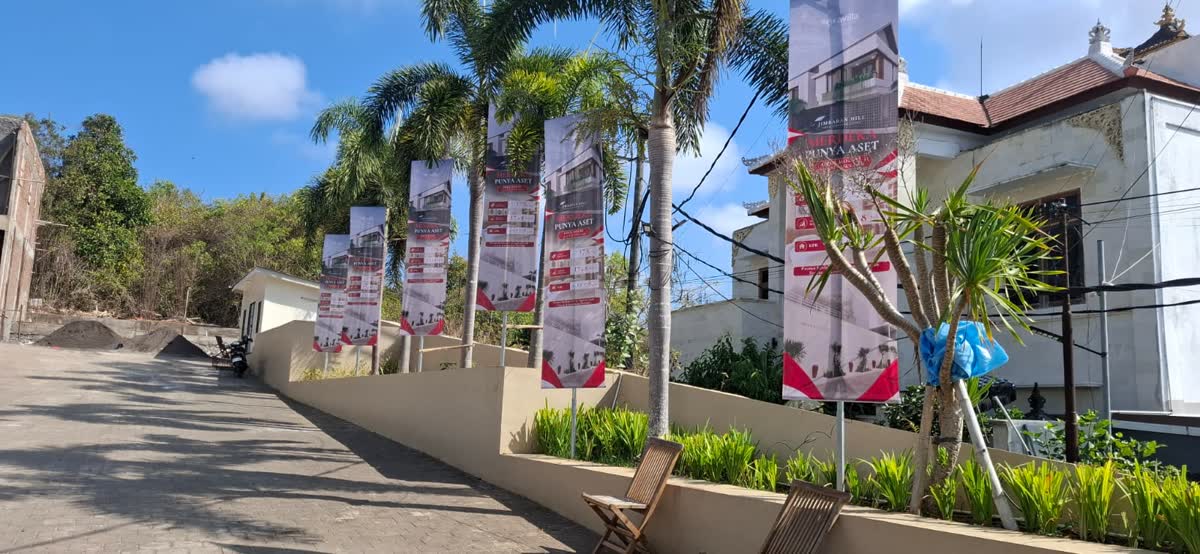
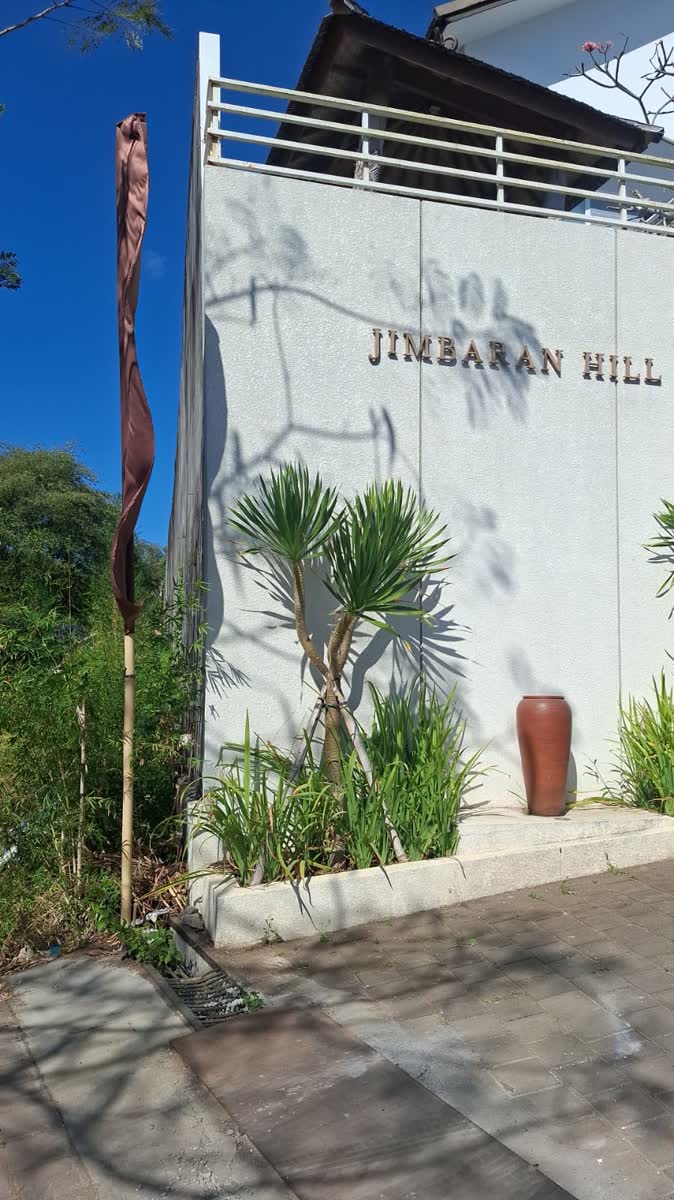
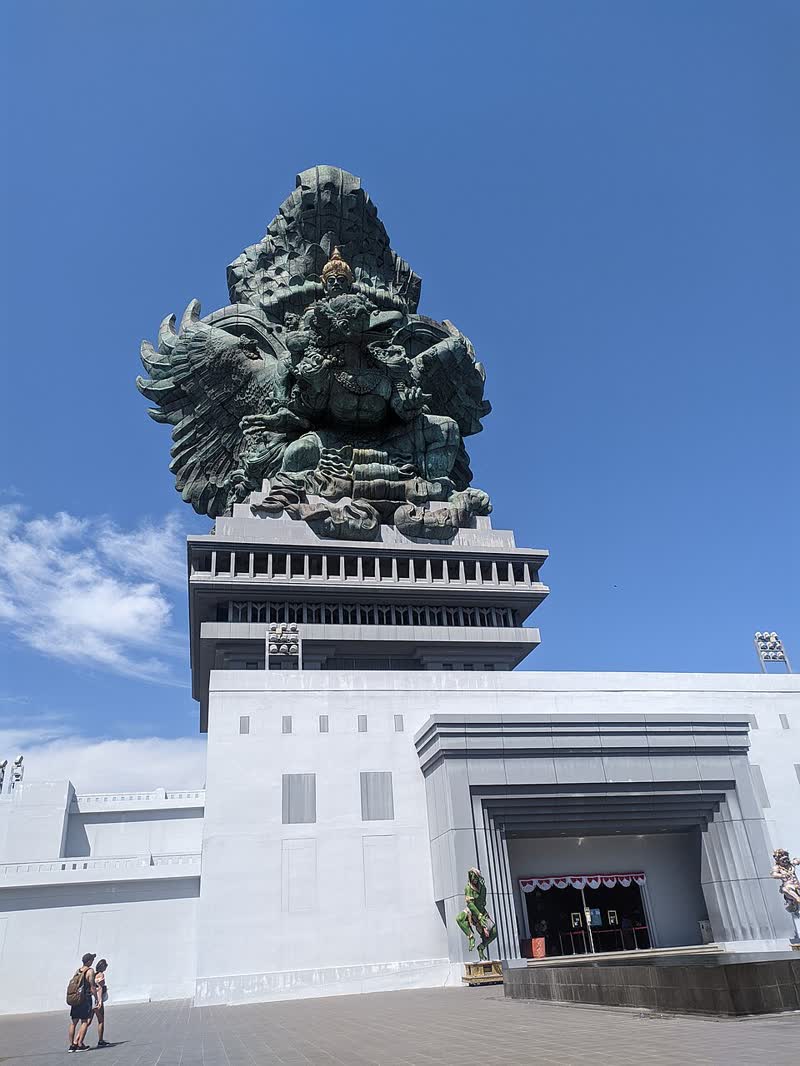
The estate (kawasan) and its entrance, photographed today. Right: GWK, minutes away — photo Dare2Leap, CC BY-SA 4.0, Wikimedia Commons.
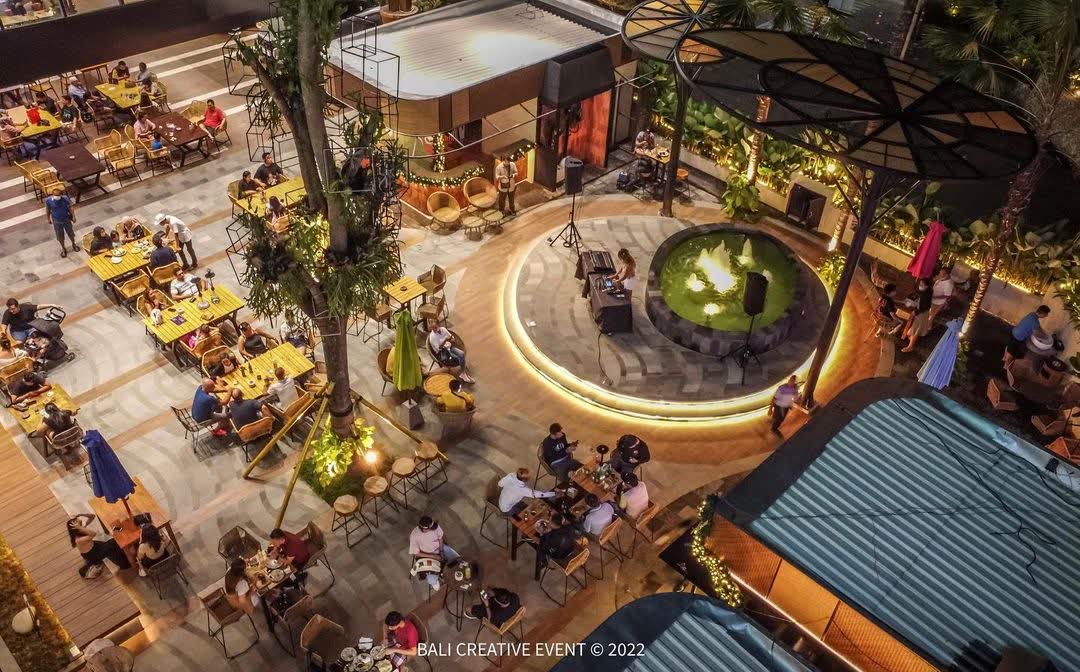
Left: Sidewalk Jimbaran, 5 minutes away — photo © Bali Creative Event. Right: the exact location — zoom and explore.
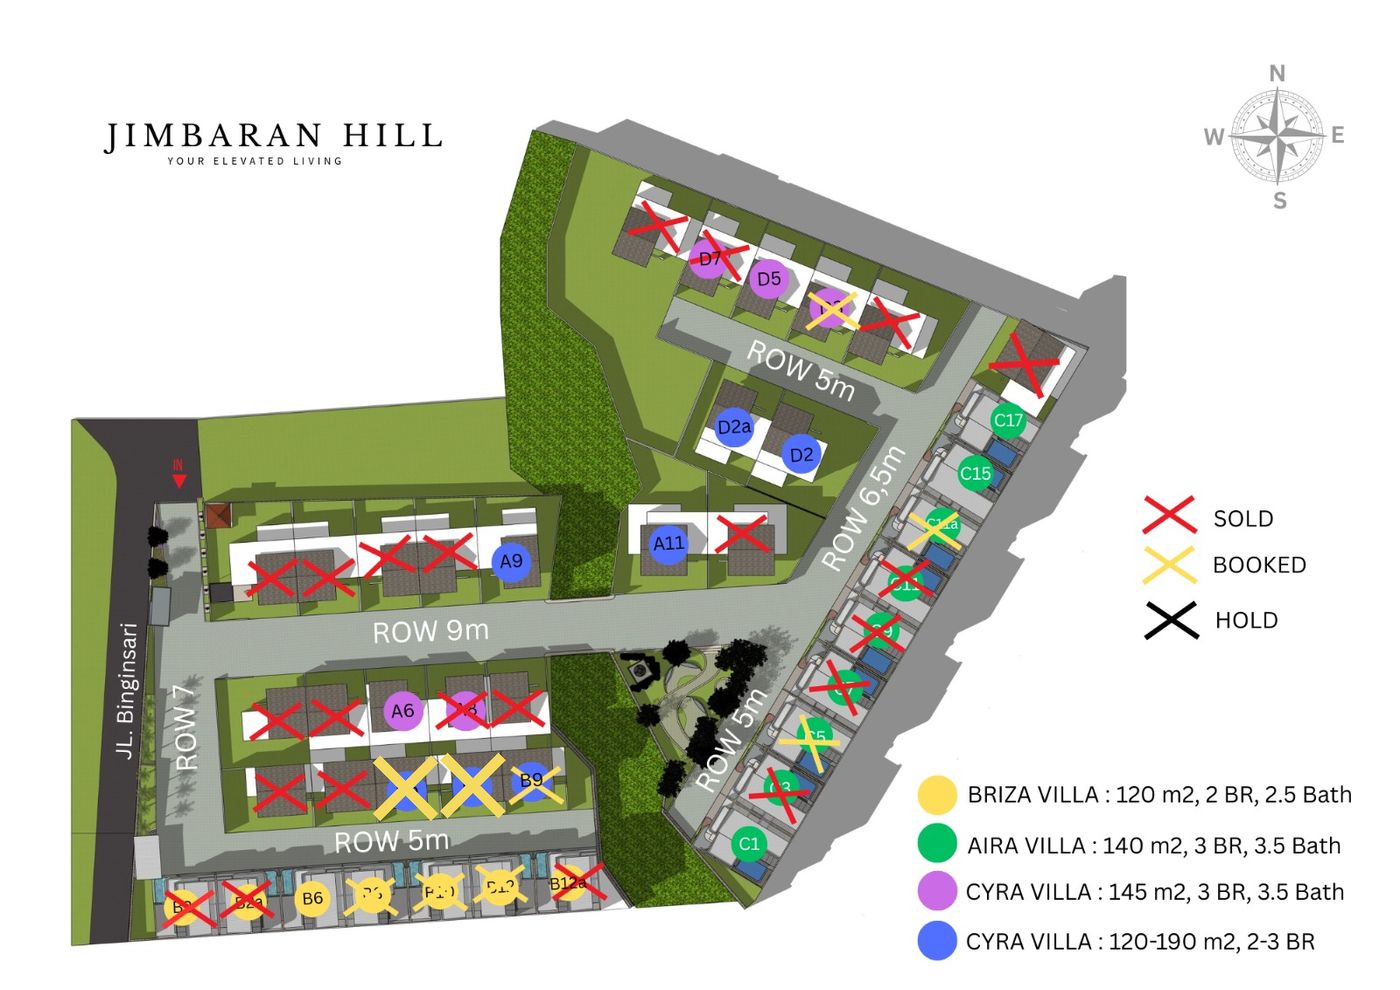
The site plan, with sold and booked units marked. Availability moves — ask us for the live status.
Which costs are yours depends on the scheme. On Aira units C9, C15, and C17, the current promo covers PPN, the full 10% down payment, BPHTB (the buyer's transfer tax), and the AJB & balik nama notary costs — about IDR 815M in total. On Cyra units under Promo Merdeka, the DP drops to a flat IDR 178M, but BPHTB and notary costs stay on your side. On every scheme, the bank's own costs at akad and the optional add-ons — pool, pantry, furniture are not standard — are yours. Promos also end. We'll show you the real all-in number for your unit before you commit to anything.
Jimbaran Hill is built by Avilla Development, a Bali developer working since 2005 across villas, resorts, and commercial projects — restaurants and coffee shops included. Twenty years of delivered buildings you can visit matters more than any brochure promise: it's the simplest due diligence there is.
There is no universal yes — every application is assessed by the bank on its own merits. Broadly, banks look at six things:
KPR is for Indonesian citizens. A valid KTP is the non-negotiable starting point — freehold title (SHM) can only be held by WNI.
What matters is not where you earn, but whether it can be documented — payslips, contracts, bank statements the bank can verify.
Employees show tenure and an employment letter. Business owners show financials and a track record. Both routes work; the paperwork differs.
Banks check SLIK — Sistem Layanan Informasi Keuangan, the national credit registry run by OJK, Indonesia's financial authority (it replaced "BI Checking"). It records your loans, credit cards, and how you've repaid them. Unresolved bad debt there is the most common reason applications fail.
Your age at the end of the loan matters. A 20-year tenor is easier to get at 30 than at 50 — banks set their own limits.
Each bank has its own criteria and appetite, and they change. What one bank declines, another may approve.
Banks generally want your total monthly installments — this loan plus any others — to stay within roughly 30–40% of your documented monthly income. Against the example installment of ±IDR 19.5M, that points to an income of around IDR 49–65M per month, or its equivalent in your working currency. It's a rule of thumb, not a rule: the bank's own calculation is the one that counts.
Living in Singapore, Australia, or Europe? You may still be able to apply for KPR, subject to the bank's assessment and documentation requirements. A foreign-currency salary means more paperwork — not disqualification. And if the currency you earn in has strengthened against the rupiah, your income may go further here than you think. You wouldn't be the first, either: several buyers in this project earn their income overseas.
A worked example on a real unit under Promo Merdeka, line by line, in the same format the developer uses — so you can see exactly what you pay, and when. Every figure is an estimate for illustration; your actual numbers depend on the unit, the bank's assessment, and rates at the time of application.
| Luas tanahLand size | 130 m² |
| Luas bangunanBuilding size | 125 m² |
| Jumlah lantaiFloors | 2 |
| PosisiLot position | Hook — corner lot |
| Harga jualProperty price — includes 11% PPN (VAT) | Rp3.463.300.000 |
| Booking feeFully refundable within the 7-day cooling period, or if KPR is rejected | Rp25.000.000(-) day 1 |
| DP 10% standarReplaced by the flat promo DP below | Rp346.330.000 |
| DP — Promo Merdeka, flatMinus the booking fee already paid, Rp153.000.000 is due | Rp178.000.000(-) day 14 |
| Plafon kreditThe KPR amount the bank finances, disbursed from ± day 45 | Rp3.285.300.000 |
| Cicilan 10thEstimated installments at the promo's ± 5% p.a. effective initial rate | Rp38.962.098/120x |
| Cicilan 15th | Rp25.974.732/180x |
| Cicilan 20th | Rp19.481.049/240x |
| DP standar 10% | Rp346.330.000 |
| DP promo — flat | Rp178.000.000 |
| TOTAL HEMATWhat the promo saves you | Rp168.330.000 |
| B. provisi 1,3%The bank's loan-provision fee | ± Rp42.708.900 |
| As. kebakaran 0,05%Fire insurance on the building | ± Rp1.642.650 |
| As. jiwa ± 2,00%Life insurance covering the loan — the premium follows your age | ± Rp65.706.000 |
| Blokir cicilan 1 bulanOne month's installment held in your account as the bank's security — still yours, just blocked | ± Rp19.481.049 |
| Total Bayar IBank costs due at signing | ± Rp129.538.599(-) day 45 / akad |
| Total cash, booking → akadBooking fee + DP + akad costs, over ± 45 days | ± Rp307.538.599 |
All figures are estimates based on current assumptions — final numbers follow applicable tax rules, prevailing interest rates, and the KPR bank's own analysis. Cicilan 20th ≈ USD 1,190 / month at an indicative IDR 16,400 per USD. Not a loan offer.
The booking fee — IDR 20–25M depending on the scheme — is fully refundable for any reason within the 7-day cooling period, and refundable if the bank rejects your KPR application. You can check whether you qualify without betting money on the answer.
On these three Aira units the developer covers ± IDR 815.8M of costs: your IDR 20M booking fee counts toward the DP and the promo carries the rest, so roughly the bank's akad costs (± IDR 124M) take you to akad. Ask us which scheme fits your unit.
Unit A9 — Cyra · land 199 m² · building 150 m² · IDR 4.62B (≈ USD 282K) · long-stay rental, furnished · net annual ROI after agent fee and maintenance
A projection, not a promise — and not financial advice. Ask us for the full calculation and stress-test it with your own numbers.
Seven steps from first conversation to keys in hand. The developer's payment rhythm: booking fee on day 1, down payment within 14 days, KPR disbursement from around day 45.
A short conversation about your situation — where you live, how you earn, your credit history. Honest answers here save weeks later. If KPR isn't realistic for you, we'll say so at this step.
We send you the current checklist for your situation — domestic or overseas — and help you get it complete before anything is submitted. Incomplete files are the most common cause of delay.
Your file goes to the bank. This is also when the booking fee secures your unit — refundable within the 7-day cooling period, or if the bank says no.
The bank verifies your income, checks SLIK, and appraises the property. Typically a few weeks; longer with overseas documents. This is the step nobody can promise you through — including us.
The bank issues its offer: approved amount, rate, tenor, and terms. Read it with us before you accept — the fixed-rate period and what follows it matter as much as the headline rate.
The credit agreement with the bank and the sale documents at the notaris. This is where AJB, balik nama, and BPHTB happen — the costs we flagged above.
Construction completes and the villa is handed over — around 12 months for most units, around 8 for A6. Your SHM certificate, split to your name, is held by the bank until the loan is settled. That's how KPR collateral works.
The exact checklist depends on the bank — treat this as the shape of it, not the final list. We'll send you the current requirements for your situation before anything is submitted.
Yes — you may still be able to apply, subject to the bank's assessment and documentation requirements. You'll need a valid KTP and income the bank can verify. Overseas applications take more paperwork and usually more time, and approval is never guaranteed — but living abroad does not, by itself, close the door.
Earning in a foreign currency doesn't disqualify you. Banks care about whether your income is real, stable, and documented — contracts, payslips, bank statements. Each bank treats foreign income differently, which is why choosing the right bank for your situation matters more than it does for a domestic applicant.
Currently available units at Jimbaran Hill range from IDR 2,824,800,000 to IDR 6,091,200,000 depending on type, unit, and land size — roughly USD 172K–371K at current rates, including 11% VAT. What sits on top depends on the payment scheme: see the cost breakdown above for the honest all-in picture.
It depends on the unit's promo. Cyra units under Promo Merdeka take a flat DP of IDR 178 million — against a standard 10% that would be IDR 280–460M depending on the unit. On Aira units C9, C15, and C17 the developer currently covers the 10% DP entirely, with your booking fee counting as the first payment. Outside a promo, the standard scheme is 10%. The bank's own loan-to-value assessment always has the final say on how much it will finance.
As an illustration: unit B9 at IDR 3.46B with a flat promo DP of IDR 178M has the bank financing IDR 3.29B — roughly IDR 19.5 million per month on a 20-year tenor at the promo's estimated 5% p.a. effective initial rate. Shorter tenors mean higher installments — around IDR 26.0M over 15 years, IDR 39.0M over 10. These are estimates, not offers — rates follow the bank's current program.
The developer's bank simulations cover 10, 15, and 20-year tenors. The tenor you're actually offered depends on the bank and on your age at the end of the loan — banks set their own maximum age at maturity.
The current simulation uses a stepped fixed structure ("fix berjenjang"): the rate is fixed in tiers that rise at set intervals — lowest in the first years, stepping up afterward — rather than one flat rate for the whole loan. After the fixed period ends, the loan moves to the bank's floating rate, which changes with the market. Ask us for the current simulation before you apply, and ask the bank for its current floating rate so you know the ceiling, not just the teaser.
Most Indonesian banks charge a fee for early or accelerated repayment — as an indication, in the range of 2–3% of the amount repaid, with 2.5% being typical. The exact figure and the rules around it are written in the credit agreement — read that clause before akad, not after. We'll flag it when we review the bank's offer with you.
Largely, yes. We do video calls and live virtual tours of the estate and the Cyra show unit, documents can be prepared and exchanged remotely, and signing can often be handled through a surat kuasa — a notarized power of attorney. Some banks require your presence for certain steps, so the exact path depends on the bank; we'll confirm it for your case. Several buyers in this project completed their purchase while living and earning overseas.
Banks generally want your total monthly installments — including any existing loans — within roughly 30–40% of your documented monthly income. On the example installment of ±IDR 19.5M, that suggests an income of around IDR 49–65M per month or its equivalent in your working currency. The bank's own calculation decides; this only tells you whether a conversation is worth having. (It usually is — that's what the free eligibility check is for.)
Faster than you might expect. On this project, once you complete payment the land's SHM goes through balik nama — the title transfer at the notaris — into your name immediately. The building's certificate follows later, once it's issued. A practical consequence: the BPHTB transfer tax you pay at the start is calculated on the land, with the building portion following when its certificate does. We'll walk you through the sequence at the notaris stage.
Yes. With KPR, the property you're buying is the collateral — the bank holds the SHM certificate until the loan is fully repaid. You normally don't need to pledge any other asset.
Some banks will consider documented rental income as part of your capacity; others weigh it lightly or not at all. Your primary income carries the assessment. If you're counting on projected rental income from the villa itself to qualify — most banks won't accept that, so plan around your existing income.
Yes. The booking fee — IDR 20–25 million depending on the scheme — is fully refundable for any reason within the 7-day cooling period, and refundable if the bank rejects your KPR application. Outside those cases, the developer's standard terms apply.
We work with the developer's partner banks, and which one fits you best depends on your situation — especially if your income is overseas. Bank programs and rates change often enough that we'd rather tell you what's current when you ask than publish a list that goes stale.
The developer's schedule: booking fee on day 1, down payment within 14 days, KPR disbursement from around day 45. The bank's assessment typically takes a few weeks inside that window — longer when overseas documents need verifying. Nobody serious will promise you a faster clock.
Yes. Banks assess business owners on financial statements, business licences, and track record instead of payslips. The bar isn't higher, but the paperwork is different — usually two years or more of demonstrable business income.
Once the loan is running, it continues as long as you pay — you don't re-qualify after every career move, though your credit agreement may require you to inform the bank of material changes. Changing jobs before approval is different: banks like tenure, so if a move is coming, the timing of your application matters. Talk to us first.
This one deserves a careful answer. Freehold title (SHM) can only be held by Indonesian citizens. If you renounce your citizenship, Indonesian law generally requires the right to be transferred or converted within a set period — and your change of status affects the loan too. This is general information, not legal advice: if a citizenship change is on your horizon, discuss your specific situation with us and a notaris before you buy, not after.
Tell us a little about your situation and we'll help you understand the next steps — honestly, including if KPR isn't your best option. If you're overseas, we'll book a video call and take you on a live virtual tour of the property.
KPR approval is subject to bank assessment and applicable requirements. Figures on this page are estimates for illustration and do not constitute a loan offer, or legal or financial advice.